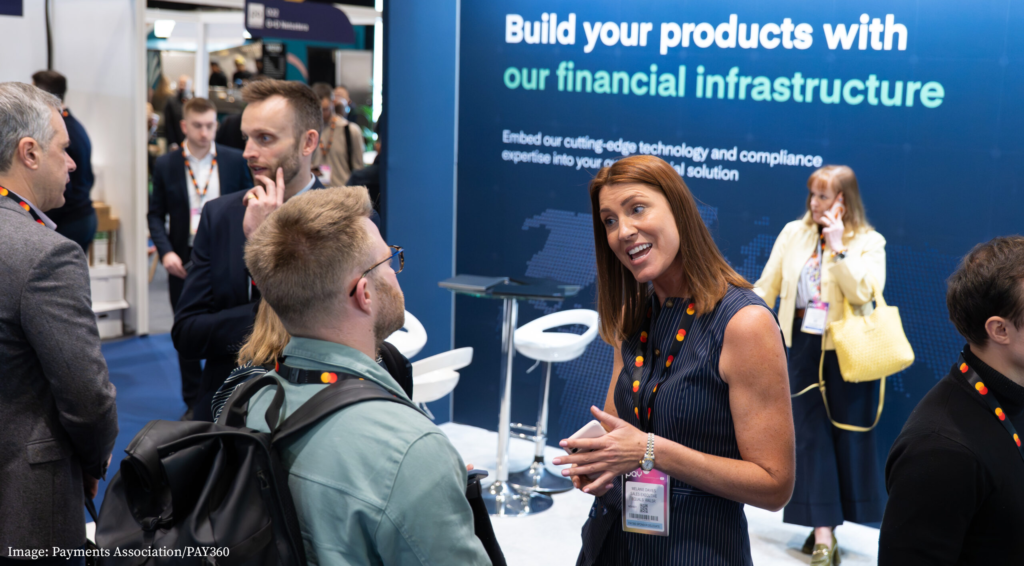
Pay360 brings together the fintech ecosystem of global payment networks, electronic money institutions, start-ups and service provide, so it’s the perfect place to take the temperature of the sector near the start of the year
Curated and moderated by the editorial team at The Payments Association, the conference offers a snapshot of the state of payments each March, with keynote speakers from government, the Financial Conduct Authority (FCA), major banks and digital asset providers.
We identified four key themes that ran through discussions across the event. Here’s our take on what they mean for marketing and comms professionals in the sector.
Most exhibitors at Pay360 deliver the invisible infrastructure that underpins payments. Yet success is judged on the end user’s experience: whether a business or a consumer.
“Customers don’t care about the bank; they care about the experience,” declared First Direct’s Saira Khan in the opening panel.
Lou Murray, CSO of Equals Money | Railsr, echoed the sentiment in her conversation with ANNA Money co-CEO Boris Diakonov at the other end of the day: “SMEs want products and experiences that work,” she said. Diakonov, who founded the business accounting and tax app added: “Small business owners don’t worry about payments until something breaks, but they do worry about keeping on top of taxes.”
The smooth running of the invisible infrastructure that keeps the money flowing is what keeps most Pay360 delegates up at night. For their marketing and communications colleagues, the challenge is to demonstrate how this behind-the-scenes technology delivers tangible outcomes using customer stories, operational data and proof points.
Fintech was among the earliest adopters of AI, which is already enabling faster, smoother payment experiences. The next step-change is agentic payments: AI completing transactions on behalf of individuals or businesses.
Following Mastercard’s initial rollout of agentic payments in 2025, the FCA acknowledged on the opening morning of Pay360 that a regulatory approach to this new wave of innovation is needed.
“Money is moving faster and faster—but is it moving safer?” asked Chris Skinner, fintech author and commentator at The Finanser.
“AI agents can hallucinate,” warned Michael Borrelli, Director at AI & Partners. “You need to be able to identify when drift begins: for example, when a chatbot starts giving a vulnerable customer poor advice.”
How should financial services providers respond?
“We need to move towards an evidence-based regulatory regime, rather than a process-based one,” said Warren Russell, RegTech entrepreneur at eyeDP.
“You need to document rationale, because things will go wrong,” agreed Dane Pedro, Head of UK Compliance and MLRO at Mollie. “And you will always need a human to train the AI.”
“It comes down to collaboration between teams and understanding the customer impact,” said Bushra Saba, Lead Data Architect for Economic Crime Prevention at Lloyds Banking Group. “The FCA is very outcomes-based, and Consumer Duty is always a consideration. It’s about collaboration, transparency and documentation.”
Are consumers ready for agentic payments?
Trust will be earned by solving real customer problems, said NVIDIA’s payments lead, Georgios Kolovos: “You need to address a genuine customer need.”.
Fintechs are already demonstrating the potential of agentic AI. For banks and other financial service providers, there’s a significant opportunity in landing this right with customers, and an equally big risk in getting it wrong. The media are already publishing regular horror stories of AI bots gone wild. Communications teams need to do more than promote tech innovation; they must demonstrate control through case studies, data-led proof points and clear regulatory alignment, articulating both the benefits of agentic payments and the safeguards in place to protect customers.
If stablecoin felt like an emerging topic last year, this year its use cases have come into sharper focus.
“We see two primary use cases,” saidCircle VP Sanja Kon. “Providing payment corridors in regions that are difficult to transact in, and enabling stored value in emerging markets.”
“Every region is building its own digital infrastructure,” she added. “Companies need to operate across systems that are not always interoperable. Stablecoins offer a unified stream of digital dollars that can be used globally.”
Singapore-based Thunes has partnered with Circle to embed stablecoins into its infrastructure. “This has enabled us to unlock trapped liquidity, optimise working capital and manage FX volatility,” said CRO Andrew Stewart. “Businesses require real-time clearing and flexibility. Stablecoins allow us to pre-fund and unlock always-on liquidity.”
A separate Circle interview with Nika Naghavi from Zepz, highlighted similar benefits for treasury management and remittances.
Yet, regulatory concerns have persisted, with policymakers on both sides of the Atlantic raising questions about stability and risk. For many outside the industry, stablecoin still sits in crypto’s shadow.
In the opening discussion of the conference, Luke Charters MP announced the Labour government’s plans to ban crypto donations to political parties. Riccardo Tordera-Ricchi, Director of Policy & Government Relations, was in shock. “Continuing to associate crypto with criminal activity sends the wrong message about the UK”, he told us.
Since the introduction of frameworks such as MiCA in the EU and the US GENIUS Act, however, Circle has seen a 70% month-on-month acceleration in use cases . “A bank can lend a dollar multiple times,” Kon noted, “but stablecoins must be fully backed 1:1 with cash equivalents. It’s a safer form of money.”
After the hype of 2025’s “stablecoin summer”, firms are now competing to show how they can use blockchain to deliver better payments. In the heat of innovation, however, it’s easy to forget that wider understanding may lag behind. The challenge for communications teams is to close the gap between technical capability and public perception: reframing stablecoins around real-world utility, while actively addressing the regulatory and reputational concerns that still shape mainstream coverage.
James Hurren, data journalist at The Payments Association, highlighted four major challenges identified in the G20’s Cross-Border Payments Roadmap: blockers created by correspondent banking, speed, accessibility and transparency. Solutions, he argued, will come from a combination of stablecoins, account-to-account transfers, new software and regulation.
Progress varies by region. In the UK, Faster Payments and the National Payments Vision are driving speed and cross-industry collaboration. In the EU, SEPA now enables instant cross-border payments within the bloc.
“Eighty per cent of transaction time is spent in the last mile,” said Natwest’s Head of Payments Damian Richardson. “This is where delays occur, often due to local requirements or limited banking hours.”
As a result, many fintechs are focusing on improving processes such as screening, anti-money laundering (AML) and know your customer (KYC).
With stablecoin offering another alternative to traditional payment rails, the challenge now is how to keep money flowing smoothly across an increasingly diverse range of systems.
Emma Hagan, CEO of ClearBank, warned that digital assets will not wait for a new cross-border network: “We could see a two-tier system. Innovation is likely to run ahead of regulation.”
Networks like Swift and Circle are competing to demonstrate how they’re best positioned to support interoperability. Nick Kerrigan, Swift’s MD and Head of Innovation, was on the front foot. He described its ledger as “an orchestration layer across existing and future systems.”
“The technology is the easy part,” Richardson added. “Regulation is harder. A globally agreed screening standard would allow approvals in one market to be recognised in another.” He noted that the global shift towards harmonised standards such as ISO 20022 is a step in that direction.
All stakeholders agree that international cooperation will be critical to addressing cross-border challenges. With the UK set to host the G20 in 2027 and Bank of England Governor Andrew Bailey chairing the Financial Stability Board, pressure on both industry and regulators is likely to intensify. The comms opportunity is to demonstrate the role the businesses we’re working with play in finding solutions.
At a time of global trade tensions and conflict, the payments ecosystem showcased at Pay360 offers a compelling example of an industry working together to deliver innovation that improves lives and makes business easier.
Yet competition remains intense. Across the exhibition floor, multiple providers are tackling the same challenges, and we regularly hear of once-promising fintechs that have failed to scale.
The conference made one thing clear: innovation in payments is no longer judged by what technology can do, but by how it performs to deliver customer outcomes. This requires consistent evidence-building. Brands must demonstrate how their technology enhances experiences, protects customers and solves real-world problems, particularly in the context of AI and evolving regulation.
To stand out, fintechs need a distinctive and repeatable way to prove this through data, storytelling and third-party validation, delivered consistently until it cuts through.
If you’d like to discuss how these trends translate into a differentiated communications strategy, get in touch with Chris Baker, Senior PR Consultant: 07983 079640 | [email protected]